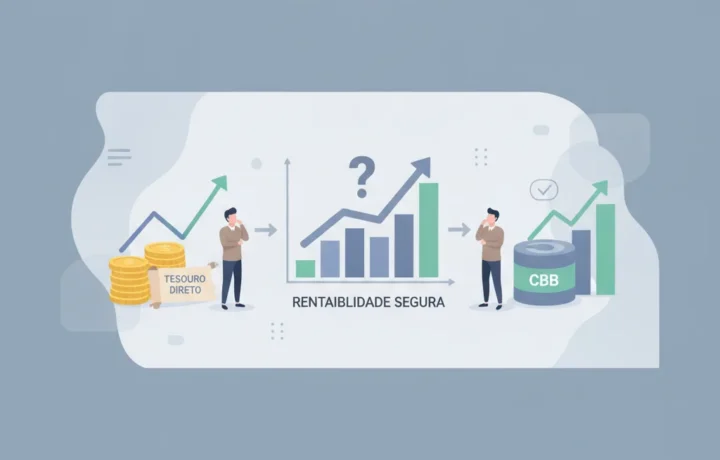
If you are looking for investment options with safety and good returns, you have probably come across Tesouro Direto and CDB. Both are very popular among investors who want to protect their money and still earn gains. But which one offers the best safe return? In this article, we will explain the characteristics of each investment to help you make the best decision.
What Tesouro Direto and CDB are and how they work
Tesouro Direto is a public bond issued by the federal government. When you invest, you are lending money to the Union, which commits to pay the invested amount plus interest within a set term. There are bonds with fixed, post-fixed or inflation-linked returns.
The CDB (Bank Deposit Certificate) is a security issued by banks and fintechs to raise funds. You also lend money, but to the financial institution. The bank pays interest on the invested amount over the agreed term. CDBs can be prefixed, post-fixed or indexed to inflation.
Advantages and benefits
Tesouro Direto is known for its high safety, as it is backed by the federal government. Its bonds usually offer daily liquidity, allowing redemptions at any time, although the ideal is to invest until maturity to maximize gains.
CDBs can offer attractive returns, especially when issued by smaller banks or fintechs, which often pay better rates. In addition, these securities are protected by the Credit Guarantee Fund (FGC) up to R$ 250 thousand per CPF and institution.
Precautions and points of attention
With Tesouro Direto, the return can vary depending on the type of bond chosen. There are custody fees and possible taxes such as Income Tax, which applies to earnings according to the investment period.
With CDBs, it is important to assess the financial health of the issuing bank and the maturity term. As the FGC protects up to a certain amount, investing above that limit in a single institution can increase risk. Income Tax also applies.
How to apply for or start investing
To invest in Tesouro Direto, open an account with a reliable brokerage or investment bank, such as BTG Pactual, Ágora or XP. With an active account, you can buy the bonds through the official website or app.
For CDBs, digital banks such as Inter, Next and PagBank, as well as traditional banks, offer CDBs with varied conditions. It is important to compare rates and grace periods before deciding.
Conclusion
Both Tesouro Direto and CDBs are great options for those seeking safe investments with good returns. Tesouro is ideal for those who want full government guarantee and daily liquidity, while CDBs can stand out for their returns, as long as you observe FGC limits and the term.
Analyze your profile and goals, and consider diversifying among these products to balance risk and return. This way, you will have more peace of mind and potential to reach your financial goals.